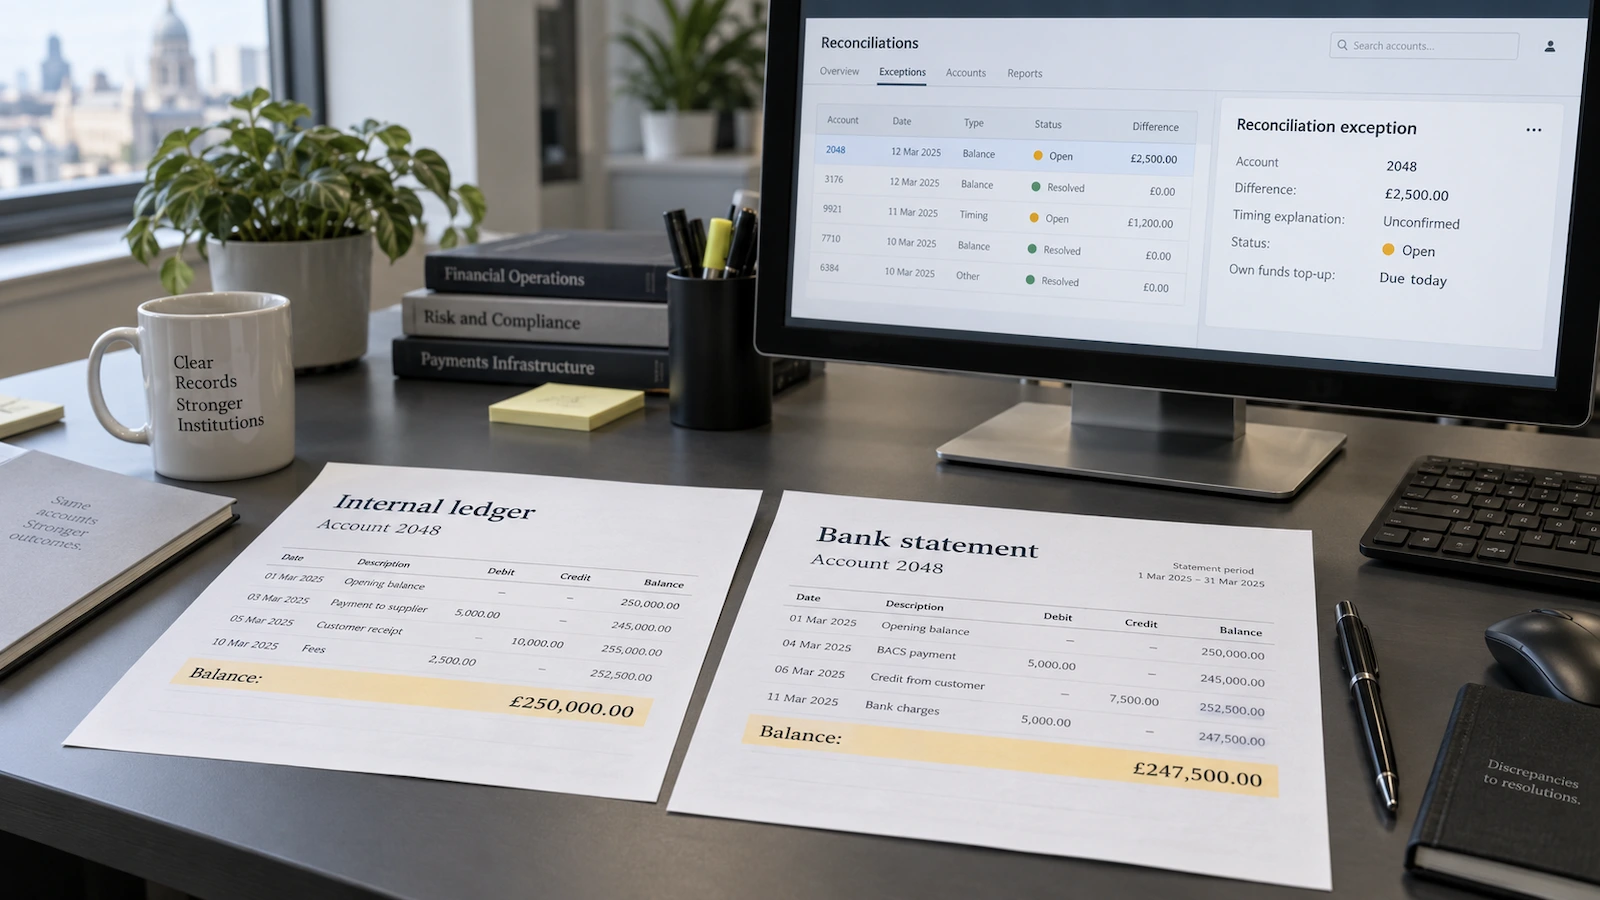
A difference is not an exception
One respondent to CP24/20 asked the FCA to review its use of the terms differences and discrepancies and make them consistent. In Policy Statement PS25/12, published on 7 August 2025, the FCA recorded the request and confirmed it had amended the reconciliation rules so that they refer to discrepancies consistently. The rulebook that came into force on 7 May 2026 carries one term where the consultation draft had carried two.
Reconciliations check the accuracy of a firm’s books and records rather than serving as the means of maintaining them, the FCA reminded firms in the same document. A system that learns its own correct balance by reconciling to a counterparty statement holds no independent record to compare against, and no discrepancy is capable of arising from it. Whether a firm holds two genuinely separate records is settled by its ledger architecture, not by its reconciliation procedure.
An exception is not a difference that failed to match. It is a difference carrying a recorded time, a recorded set of actions, a recorded outcome of the underlying calculation, and, in most regimes, a funding consequence that lands before the end of the same day.
PCAOB AS 2301.49 requires an auditor who identifies items needing further investigation during a test of details to treat the investigating procedures as part of the response to assessed risk, and to determine whether those items, individually or in aggregate, indicate misstatements or deficiencies in internal control over financial reporting. The standard closes on a choice between two named outcomes. An identified item that has not been assigned to one of them has not been investigated.
The word is “solely”
CASS 15.8.56R requires a safeguarding institution to investigate the reason for any discrepancy identified by an external safeguarding reconciliation and take all reasonable steps to resolve it without undue delay. The rule then carves out one case: where the discrepancy arises “solely as a result of timing differences” between the accounting systems of the party issuing the statement and those of the institution. The exemption turns on a single adverb. A discrepancy that is mostly timing is not solely timing, and nothing in the rule reduces the obligation in proportion.
CASS 15.8.57R sets the price of failing that test. Where an institution cannot immediately resolve a discrepancy and one of the records it examined indicates that more relevant funds should be held than are in fact held, it must assume that record is accurate until the matter is finally resolved, and pay in its own money. The firm funds the gap between its two records from its own balance sheet, and keeps funding it for as long as the classification remains unsettled.
CASS 15.8.50R runs a tighter clock on the internal side, requiring any shortfall between safeguarding resource and safeguarding requirement to be paid into a relevant funds bank account or invested in relevant assets as soon as possible, and in any case by the end of the day on which the reconciliation is performed. Where the D+1 segregation resource falls below the D+1 segregation requirement and relevant funds cannot be used to close it, CASS 15.8.51R(2) directs the firm to use its own funds even where doing so creates a fresh discrepancy between requirement and resource.
What the break record has to contain
CASS 15.8.9R lists four things a safeguarding institution must record for every internal and external safeguarding reconciliation it performs: the time and date it carried out the process; the actions it took in carrying it out; the outcome of its calculation of the safeguarding requirement and, where relevant, the safeguarding resource; and, where relevant, the outcome of its comparison of the D+1 segregation requirement and resource. Records made under the chapter are retained for five years from creation or last modification under CASS 15.8.8R(3). The list specifies the actions. It does not specify the actor.
SEA Rule 17a-13(b)(5) gives a US broker-dealer seven business days after each required quarterly securities count to record every unresolved difference in a security count difference account, identifying the security involved and the date of comparison. FINRA Rule 4522(b)(2) restates the deadline for carrying and clearing members. The unresolved difference does not sit in a queue or in a spreadsheet tab of the operator’s own naming. It sits in an account on the books, where the firm’s examining authority knows to look for it.
Swift’s CBPR+ roadmap, version 5 of June 2026, removes the free-text option from cross-border investigations. Exceptions and investigations move to camt.110 and camt.111 through Case Management: mandatory to receive camt.110 by November 2026, and mandatory to send and receive camt.110 and camt.111 by November 2027, at which point in-flow translation ends. MT 195 and MT 295 map to camt.110, MT 196 and MT 296 to camt.111, and the free-format MT 199, MT 299 and MT 999 are retired for exceptions and investigations. A query a correspondent could previously raise in prose becomes a structured message with defined fields routed through a central orchestrator, and the reason for the query becomes a value rather than a sentence. An operator who explains an investigation and its closure in narrative today has to express the same content in fields by November 2027, which is already the form investigation and closure records take on the compliance side.
Swift also states that conversion of MT 9xx statement messages into their camt equivalents is not possible, and instructs institutions to engage with their counterparts ahead of the November 2027 mandatory-receive date to agree formatting and reconciliation requirements. No translation service stands behind camt.053 the way one stands behind camt.110.
Who classifies, and who can still be asked
AS 2301.49 took effect for audits of financial statements for fiscal years beginning on or after 15 December 2025, which puts the first full calendar-year populations under it now. It is written without reference to how the items were identified. An item surfaced by a technology-assisted analysis run across a whole population and an item surfaced by a clerk both require the auditor to determine whether they indicate a misstatement or a control deficiency, and both require procedures the auditor can describe afterwards.
Microsoft’s documentation for the Account Reconciliation Agent in Dynamics 365 Finance, updated on 17 July 2026, describes how far automated classification currently reaches. The page is titled production ready preview, is marked prerelease, and states that the Microsoft team must activate the agent on request. The agent processes two exception types, voucher amount mismatch and pending accounting transferred to general ledger, and recommends an action only for the first. Where it does recommend, the disposition is chosen from a closed list of four: create journal entry, reverse, link transactions, or accept without change. Agent activity appears in the timeline as a suggested fix, and a reconciled item can be undone, which returns the exception to an unmitigated state.
Microsoft’s release plan overview for the 2025 wave described the work as continuing the agent’s preview rather than releasing it, and the product documentation as at 17 July 2026 still carries prerelease status and activation on request. What a preview already determines is what a reviewer is offered, and the second of the four dispositions on offer is accept without change, which closes a difference on the record and is a classification whether or not the person selecting it treats it as one.
Microsoft states that it may automatically update the model used by the service, so the model that generated a response may differ from the one displayed in the interface. A recommendation produced in March cannot be re-derived in November by putting the same question to the same system. Only the record made at the time survives, and CASS 15.8.9R requires the actions taken to be recorded without caring who took them. Microsoft’s documentation supplies the operative detail: every exception is logged with the history of actions taken by users, automation, or agents, which is the record evidence and exception controls rely on to establish which of the three closed a given difference.
What an unresolved difference costs before anyone explains it
A shortfall identified by an internal safeguarding reconciliation is funded by the end of the same day. A discrepancy from an external reconciliation that cannot be resolved immediately is funded from the firm’s own money until it is. A failure of the classification step itself is separately notifiable: CASS 15.8.60R requires a safeguarding institution to inform the FCA in writing without delay if it will be unable to, or materially fails to, remedy a discrepancy after an internal reconciliation, or to identify and resolve discrepancies after an external one. Not resolving a break is an operational fact. Being unable to resolve one is a reportable event, and the report goes to the regulator rather than to a queue owner.
Seven business days is what a US broker-dealer has to record the unresolved difference in the difference account. Thirty calendar days pass before the market value of a short securities count difference enters the customer reserve formula as a credit under Exhibit A to Rule 15c3-3, increasing the amount the firm must hold on deposit. Forty-five calendar days after the count, under Rule 15c3-3(h), every short security difference still unresolved must be bought in. At no point does the rule ask whether the difference was ever explained. It prices the failure to resolve it.
PS25/12 records that for payments and e-money firms that became insolvent between the first quarter of 2018 and the second quarter of 2023, there was an average shortfall of 65% between funds owed to clients and funds safeguarded. The same document records what happened when an audit standard was introduced for CASS firms in 2016: adverse audits initially rose to 142, or 13% of the population, and had fallen to 64, or 6%, by 2024. The population that fails a records test is measurable, and it moves once somebody tests it.
The FDIC’s rulemaking on recordkeeping for custodial accounts, which would require internal controls sufficient to ensure custodial account balances are accurate and reconciled no less frequently than as of the close of business daily, was published at 89 FR 80135 on 2 October 2024, and its comment period closed on 16 January 2025 after a 45-day extension. As at 7 September 2026 no final rule has been published. Daily reconciliation of a custodial deposit account is, in the United States, a supervisory expectation and a proposed obligation rather than a rule.
No supervisor publishes a figure for the share of reconciliation breaks closed without a recorded reason. The percentages in circulation come from vendor surveys and product marketing, and none of them states the population it measured.
Source register
- Financial Conduct Authority — PS25/12: Changes to the safeguarding regime for payments and e-money firms, policy statement, 7 August 2025. Supports: the consultation request to make the use of differences and discrepancies consistent, and the amendment of the reconciliation rules to refer to discrepancies consistently; reconciliations checking the accuracy of a firm’s books and records rather than serving as the means of maintaining them; an average shortfall of 65% between funds owed to clients and funds safeguarded across firms that became insolvent between the first quarter of 2018 and the second quarter of 2023; adverse CASS audits rising to 142, or 13% of the population, after the 2016 audit standard and falling to 64, or 6%, by 2024; commencement of the new regime on 7 May 2026.
- Public Company Accounting Oversight Board — AS 2301: The Auditor’s Responses to the Risks of Material Misstatement, paragraph .49, amendments effective for audits of financial statements for fiscal years beginning on or after 15 December 2025, text as at 7 September 2026. Supports: treatment of the procedures investigating identified items as part of the auditor’s response to assessed risk; the requirement to determine whether identified items, individually or in aggregate, indicate misstatements or deficiencies in internal control over financial reporting; the standard’s silence on how the items were identified.
- Financial Conduct Authority — CASS 15.8: Records, accounts and reconciliations, Handbook rules and guidance, in force 7 May 2026, text as at 7 September 2026. Supports: investigation and resolution of external reconciliation discrepancies without undue delay, and the carve-out where a discrepancy arises solely from timing differences between the two accounting systems (15.8.56R); the obligation to assume the record showing the greater requirement is accurate and to pay in the institution’s own money until final resolution (15.8.57R); payment of shortfalls by the end of the day on which the reconciliation is performed (15.8.50R); use of own funds to close a D+1 shortfall even where doing so creates a fresh discrepancy (15.8.51R(2)); the four elements recorded for every internal and external safeguarding reconciliation (15.8.9R); five-year retention of records made under the chapter (15.8.8R(3)); written notification to the FCA without delay on inability or material failure to remedy, or to identify and resolve, discrepancies (15.8.60R).
- US Securities and Exchange Commission — 17 CFR 240.17a-13: Quarterly security counts to be made by certain exchange members, brokers, and dealers, text as at 7 September 2026. Supports: recording of every unresolved difference in a security count difference account no later than seven business days after each required quarterly count, identifying the security involved and the date of comparison (paragraph (b)(5)).
- FINRA — Rule 4522: Periodic Security Counts, Verifications and Comparisons, rulebook, text as at 7 September 2026. Supports: the seven-business-day deadline for entering unresolved differences into a difference account as it applies to carrying and clearing members (paragraph (b)(2)).
- Swift — CBPR+ roadmap beyond November 2025, version 5, migration roadmap, June 2026. Supports: camt.110 mandatory to receive by November 2026, and camt.110 and camt.111 mandatory to send and receive by November 2027 through Case Management, at which point in-flow translation ends; the mapping of MT 195 and MT 295 to camt.110 and of MT 196 and MT 296 to camt.111; retirement of MT 199, MT 299 and MT 999 for exceptions and investigations; the impossibility of converting MT 9xx statement messages into their camt equivalents; the instruction to agree formatting and reconciliation requirements with counterparties ahead of the November 2027 date.
- Microsoft — Account Reconciliation Agent (production ready preview), Dynamics 365 Finance product documentation, updated 17 July 2026. Supports: prerelease status and activation by the Microsoft team on request; the two processed exception types, voucher amount mismatch and pending accounting transferred to general ledger; recommendation of an action only for voucher amount mismatch; the four available dispositions of create journal entry, reverse, link transactions, and accept without change; agent activity shown as a suggested fix, and the undo that returns an exception to an unmitigated state; logging of every exception with the history of actions taken by users, automation, or agents; automatic updates to the model used by the service.
- Microsoft — Overview of Dynamics 365 Finance 2025 release wave 1, release plan, text as at 7 September 2026. Supports: the wave described as continuing the preview of the account reconciliation agent rather than releasing it.
- US Securities and Exchange Commission — 17 CFR 240.15c3-3: Customer protection, reserves and custody of securities, text as at 7 September 2026. Supports: the buy-in of every short security difference still unresolved 45 calendar days after the count (paragraph (h)).
- US Securities and Exchange Commission — 17 CFR 240.15c3-3a: Exhibit A, formula for determination of customer and PAB account reserve requirements, text as at 7 September 2026. Supports: the market value of short security count differences over 30 calendar days old entering the reserve formula as a credit.
- Federal Deposit Insurance Corporation — Recordkeeping for Custodial Accounts, notice of proposed rulemaking, 12 CFR Part 375, RIN 3064-AG07, 89 FR 80135, 2 October 2024. Supports: the proposed requirement for internal controls sufficient to ensure custodial account balances are accurate and reconciled no less frequently than as of the close of business daily. The absence of a final rule rests on a check of the Federal Register made on 7 September 2026, not on this document.
- Federal Deposit Insurance Corporation — Recordkeeping for Custodial Accounts; Extension of Comment Period, notice of proposed rulemaking, extension of comment period, 20 November 2024. Supports: the 45-day extension of the comment period and its close on 16 January 2025.
· Practitioner Notes
All Insights