Payments
Execution, messaging, settlement, ledgers, and reconciliation.
Every transaction runs through two operating systems that were built separately. One moves the money. The other decides whether it should move, and has to evidence that decision long after it has moved. DELCOS documents both: which participant holds authority at each step, which record governs when two systems disagree, where a control sits and who answers for it, and how a failure propagates once it starts.
DELCOS publishes in two layers. Permanent pages own the stable subjects — a system, a mechanism, a control, a boundary of responsibility — and each is kept current against the sources behind it. Insights takes something specific and recent, a named failure or a regulatory change, and works back to the systems that produced it. Both describe how the infrastructure operates; neither gives advice on a financial decision.
Payments
Execution, messaging, settlement, ledgers, and reconciliation.
Compliance
Identity, screening, monitoring, investigations, and controls.
Transaction lifecycle
The operating layer where payment and compliance systems meet.
Insights
Cases, architecture, regulation, and practitioner analysis.
Sources and evidence
Primary records establish rules, states, responsibilities, and outcomes.
Payments and Compliance divide the stable material between them. Each hub maps its domain and routes to the system pages beneath it. The depth lives there.
How an instruction acquires authority, reaches a counterparty institution, settles, and leaves a record that survives challenge. The systems below divide that work, and each holds one part of it.
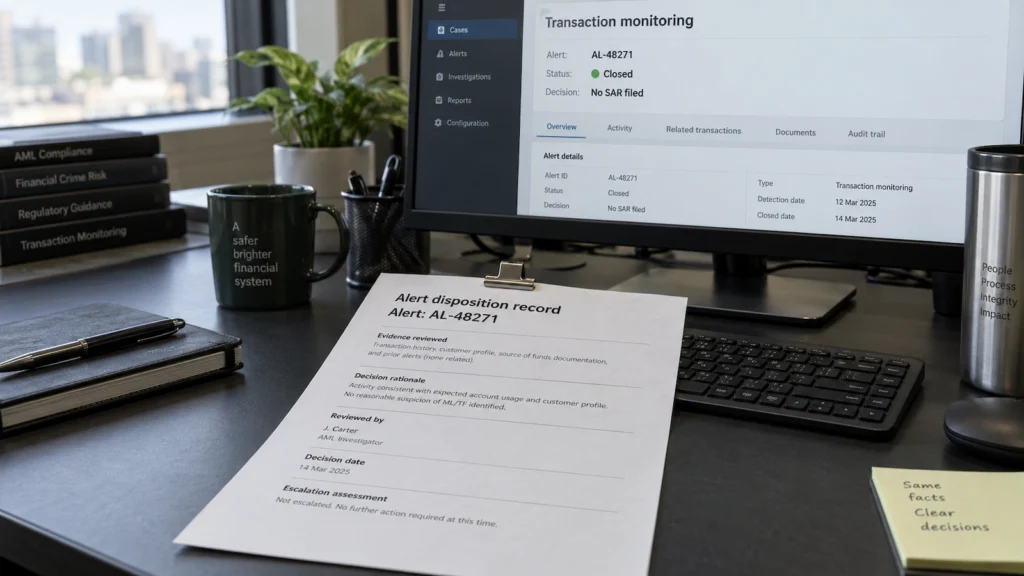
Compliance runs on what an institution can demonstrate afterward. Which participants it identified, what it monitors, how a signal became a decision — each has to remain provable to an examiner years later. The systems below carry that chain.
The same transaction passes through both domains, at the same moments. A payment often fails because one of them assumed the other had done something.
A payment enters carrying an amount, a beneficiary, and an assertion about who authorized it. Validation and routing sit with the payment layer. At the same moment, the compliance layer is deciding whether this participant is one the institution has identified and whether the transaction is one it has agreed to carry. Both layers read the same message and ask different questions of it.
Before the instruction leaves, it is screened against sanctions and internal controls. A hit stops the payment. What happens next is a compliance decision — review, escalate, release, or refuse — but the cost of it accrues in payment operations, because a held payment misses a cut-off and a missed cut-off changes when value arrives.
Clearing and settlement proceed on their own logic and their own timetable. At this stage the compliance layer observes: monitoring scores what happened against expected behavior. Irrevocability arrives at a point the settlement arrangement defines, not at the point review finishes.
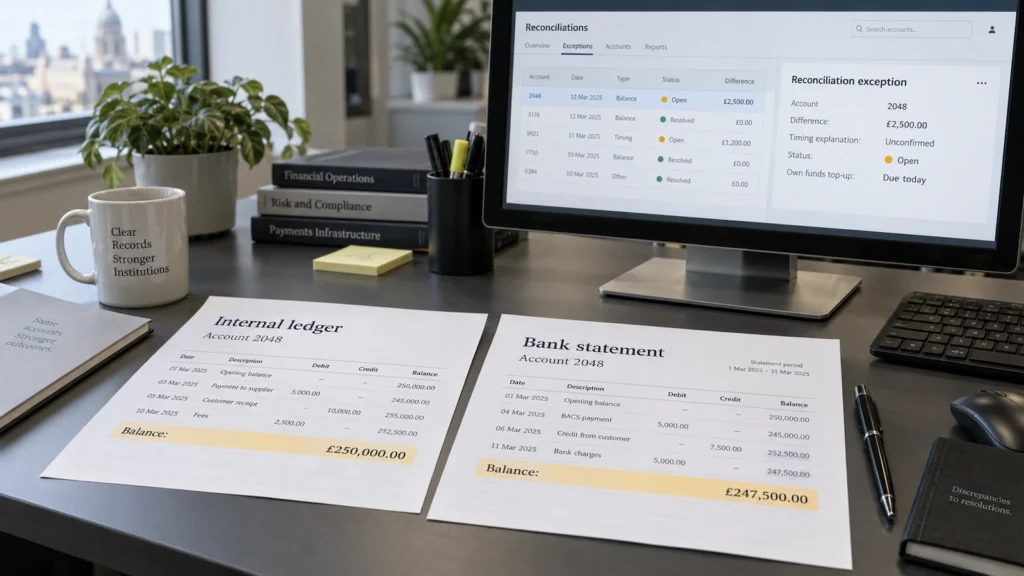
The payment layer posts and reconciles. The compliance layer retains what it decided and why. These are two records of one event, built by different teams for different reasons, and whether they can be linked afterward determines whether a dispute or an examination can be answered at all.
These crossings belong to the pages below.
Analysis of what is happening now, traced back to the systems that explain it. An article starts from something specific — a named failure, an enforcement action, a regulatory change, a pattern visible across several institutions — and works down to the permanent pages that own the mechanics. It reconstructs an event; it does not become the definition of the system underneath it.
A difference between two records costs nothing until someone decides it will not clear on its own. Under rules that came into force on 7 May 2026, that…
Read the analysisA payment that shows as received can still be taken back. Whether it can depends on which of four states it is in —…
ReadIn October 2025 five US agencies answered the question directly: an institution does not have to document a decision not to file a SAR.…
ReadThree independent counts describe the payment layer of agent-initiated commerce as at 5 September 2026. A crawler census of stores publishing the Universal Commerce…
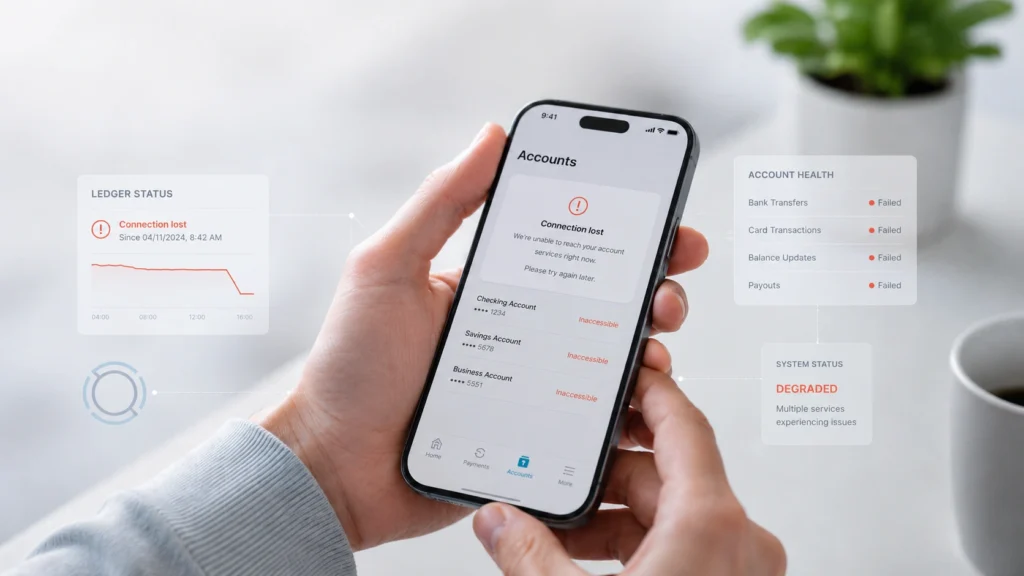
ReadIn May 2024, more than 100,000 people opened their banking apps and could not move their money. They had downloaded fintech products — savings…
ReadDELCOS is independent. It sells nothing, recommends no vendor, and has no commercial relationship with the institutions it writes about. What that independence is worth depends on what stands behind a claim.
Primary records come first here — regulation, scheme rules, court filings, official operational records, technical standards. Secondary reporting is used where primary records do not reach, and it is identified as such. The order matters. Each page carries the register of what it relied on, so a statement can be traced to the document behind it rather than to the platform asserting it. Permanent pages record when their sources were last reviewed, because material that was accurate in one rule environment does not stay accurate by default.
Each part of that work has a named person behind it, in a role that states exactly what they are answerable for.